Source: vietnambiz.vn
Forecasting economic growth for 2025, expert Nguyễn Xuân Thành believes that in a positive scenario, GDP growth could exceed 7%, potentially reaching 7.5%, if consumption improves and public investment is disbursed strongly.
Discussing the growth drivers for this year and forecasting 2025 at the October online Data Talk seminar on Economic Recovery & Trends in Reverse Capital Flows, economist Nguyễn Xuân Thành from the Fulbright School of Public Policy and Management stated that the economy could achieve better growth in 2025 compared to this year if public investment is accelerated and both consumption and private investment are improved.
Forecasting this year's growth, Mr. Thành stated that the government may confidently achieve a growth rate of 7% this year and set an ambitious target of 7.5% growth for the next year. However, to reach this goal, several issues need to be addressed.
Exports show signs of slowing down

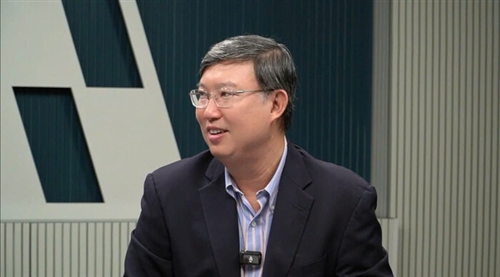
Economist Nguyễn Xuân Thành, Fulbright School of Public Policy and Management. (Image: BTC).
Regarding exports, the global economic slowdown is affecting Vietnam. Import and export activities have been slowing down since September. Although Typhoon Yagi had an impact this month, it mainly caused damage to assets, with little effect on production. "Production in provinces such as Hai Phong, Thai Nguyen, and Bac Ninh is still ongoing and hasn't been significantly disrupted, but the slowdown is evident, and in my opinion, it comes from the slowdown in exports," Mr. Thành analyzed.
It is highly likely that the major global economies will successfully curb inflation and avoid a recession in 2025, but the growth rate will decline. This is the delayed effect of maintaining high interest rates in previous years.
Thus, industrial production this year may grow by around 14%, but next year it may only grow by about 12%. Looking at electricity consumption growth, in the first nine months of the year, industrial production increased by about 11%, while electricity consumption grew by 10.7%. However, in September alone, growth was only 7%, indicating a slowdown.
"In terms of fiscal policy, I predict that next year there will be a larger public investment than this year, slightly more than in 2023. 2025 will be a year with many historic anniversaries and the final year of the current term, so policies will typically be very supportive to stimulate growth," said Mr. Thành.
According to him, the public investment disbursement this year has not met expectations. As of September 30, it is estimated that public investment disbursement has reached 320,566 billion VND, accounting for 47.29% of the Prime Minister's plan, which is lower than the same period in 2023.
However, in the next year, the final year of the term, public investment will be pushed harder to bring positive results for the economy. Additionally, 2025 will be a year with many significant anniversaries for the country, and many infrastructure projects will be rushed to complete in time for these events.
Improving sentiment to boost investment and consumption
Regarding consumption, the growth rate is lower than in previous years. There are two main reasons for this. First, the export slump last year led to a reduction or stagnation in income for some workers in export businesses, which in turn impacted consumption this year.
Second, the middle class and wealthy individuals are also tightening their spending due to challenges in the real estate market, a sluggish stock market, and issues in the financial market, such as corporate bonds.
To change the pessimistic mindset of individuals, households, and businesses, there needs to be a strong policy message that decisively addresses these challenges. This means the government must implement measures to tackle the issues causing disruptions in the financial system over the past period.
The market is still uncertain about the problems with the corporate bond market, such as how to handle overdue bonds. Companies are concerned about potential criminal liability.
"Losses are inevitable, but without a clear direction, consumers will continue to be wary of investments and savings, leading to tightened spending," said the expert.
Recent policies, such as reducing value-added tax and some other taxes and fees to stimulate consumption, can provide good momentum if maintained. However, to truly boost consumption, it's essential to maintain these tax and fee reduction policies while also sending clear messages about resolving financial system issues to alleviate the psychological "bottleneck" among the public.
Regarding investment, similar to individuals and households, for businesses, a critical message is not to criminalize economic transactions and to restore businesses' trust in the legal system.
If businesses remain concerned about legal risks, their expansion investment plans will be affected. This not only impacts short-term growth in 2024 and 2025 but also affects the mid-term growth story. "If businesses don't invest now, how can we expect mid-term growth in 2026–2027?" he said.
Therefore, there is still a scenario where growth next year could be lower than this year if the business and consumer sentiment is not improved to stimulate investment and consumption while the export and industrial production drivers slow down.
However, if consumption improves in the fourth quarter, credit increases meaningfully (not due to debt rollover), and business sentiment becomes more optimistic, the resurgence of private investment and household consumption will offset the slowdown in exports and production.
Private investment, if stimulated, will deliver much better results than growth driven by the export sector.
Interest rates may decrease in 2025
Another advantage is the monetary policy, which is currently quite favorable and has room for further easing. This year, it is clear that the Federal Reserve (Fed) will continue to ease its monetary policy by lowering interest rates, although the extent will not be significant.
It is forecasted that the Fed will cut 25 basis points in both the November and December meetings. Thus, the Fed will reduce rates by about 1 percentage point for the whole year. Next year, the expected rate reduction by the Fed is between 1% and 1.25%. After the Fed lowers its rates, central banks in Asia are also expected to follow suit, alleviating exchange rate pressures and creating room for Vietnam to lower its interest rates.
In the short term, it will be difficult for Vietnam to significantly lower interest rates in the fourth quarter, as credit is increasing sharply, while money supply growth is currently lower. The State Bank of Vietnam is targeting a 15% credit growth this year, but money supply has only increased by 12%. Therefore, if money supply is not expanded, interest rates are likely to rise, rather than decrease.
"There is no longer any exchange rate pressure, and this year the currency depreciation is only around 2%, which is very positive for monetary policy management. Additionally, inflation is not a major concern. Therefore, while interest rates may remain stable in Q4, the current environment is very favorable for reducing interest rates next year," the expert predicts.
- Hạ An
Related Articles
The 2024 Nobel Prize in Economics and Institutional Lessons for Vietnam
Dr. Vũ Thành Tự Anh: Inconsistent Adaptive Development Policies
